S Corp vs LLC for Freelancers (2026): When an S Corp Election Saves Money
In short: S corp vs LLC explained for freelancers: how an S corp election saves self-employment tax, what it costs, reasonable salary rules and when it makes sense in 2026.

On this page
- S corp vs LLC for freelancers: what’s the difference?
- How an S corp saves self-employment tax
- The costs that eat into S corp savings
- What counts as a “reasonable salary”?
- Other effects to consider
- When an S corp election makes sense
- How to elect S corp status
- S corp vs LLC for freelancers: the full math (including the QBI catch)
- How to set a reasonable salary (with a simple method)
- Retirement and the S corp vs LLC choice
- S corp election timing: when to make the switch
- S corp vs LLC: common mistakes freelancers make
- State rules that change the S corp vs LLC math
- What an LLC alone does (and does not) do
- Frequently asked questions
- Sources
“Should I be an S corp?” is one of the most common questions freelancers ask once business takes off. The confusion starts with the comparison itself: an LLC is a legal structure, while an S corporation is a tax election. You can be an LLC taxed as a sole proprietor, or an LLC that elects to be taxed as an S corp. The real question is whether S corp taxation saves you more than it costs. This guide explains S corp vs LLC for freelancers with real numbers.
Key takeaways
- LLC = legal protection and structure. S corp = how the IRS taxes your business income.
- By default, a single-member LLC is taxed like a sole proprietor: 15.3% self-employment tax on most of your profit.
- As an S corp, you pay yourself a reasonable salary (subject to payroll taxes) and take the rest as distributions (not subject to SE tax).
- Expect added costs: payroll service, Form 1120-S preparation, state taxes or fees, and more paperwork.
- You elect S corp status with Form 2553, generally within 2 months and 15 days of the start of the tax year it should take effect.
S corp vs LLC for freelancers: what’s the difference?
| LLC (default tax treatment) | LLC or corporation taxed as an S corp | |
|---|---|---|
| What it is | State legal entity | Federal tax election (Form 2553) |
| Federal tax return | Schedule C on your Form 1040 (single member) | Form 1120-S plus a K-1 to your personal return |
| How you get paid | Owner’s draws (no payroll) | W-2 salary through payroll + distributions |
| Self-employment tax | 15.3% on 92.35% of net profit (Social Security part capped at $184,500 for 2026) | Payroll taxes (15.3% combined) only on your salary |
| Paperwork | Low | Higher: payroll filings, W-2, separate return |
| Typical extra annual cost | None | Payroll service + tax preparation + possible state fees |
| Retirement contributions | Based on net self-employment earnings | Employer contributions based on W-2 salary |
How an S corp saves self-employment tax
As a default LLC or sole proprietor, you pay self-employment tax on almost all your profit. As an S corp, you pay Social Security and Medicare taxes (7.65% from you and 7.65% from the company) only on your salary. Here’s an illustrative federal comparison, before extra costs:
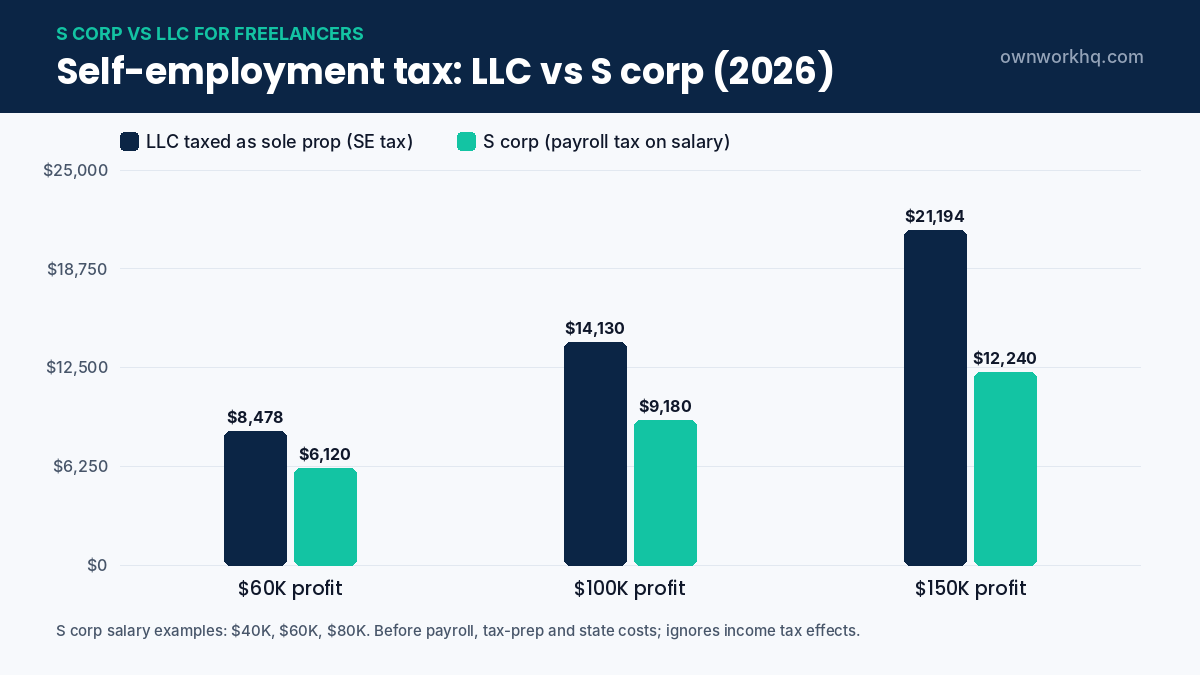
| Net profit | Reasonable salary (example) | SE tax as LLC/sole prop | Payroll taxes as S corp | Gross tax difference |
|---|---|---|---|---|
| $60,000 | $40,000 | $8,478 | $6,120 | $2,358 |
| $100,000 | $60,000 | $14,130 | $9,180 | $4,950 |
| $150,000 | $80,000 | $21,194 | $12,240 | $8,954 |
Simplified: ignores income tax effects, the QBI deduction, state taxes, unemployment taxes and the cost of running payroll. Salary figures are examples only; your salary must be reasonable for your work.
The costs that eat into S corp savings
- Payroll service: commonly several hundred dollars a year or more for a one-person payroll.
- Business tax return (Form 1120-S): professional preparation often costs more than a Schedule C.
- State taxes and fees: some states add costs. California, for example, charges S corporations a 1.5% franchise tax on net income with an $800 minimum.
- Unemployment taxes on your salary (federal and state).
- Time and compliance: quarterly payroll filings, W-2s and stricter separation of personal and business money.
Subtract these from the gross tax difference above. At $60,000 of profit, the net savings may be small or even negative. At $100,000+, they’re often meaningful.
What counts as a “reasonable salary”?
The IRS expects S corp owners who work in the business to pay themselves reasonable compensation before taking distributions. That generally means what you’d pay someone else to do your job, considering your role, experience, hours and industry. Paying yourself an unrealistically low salary to avoid payroll taxes is a common audit issue. Many freelancers use salary data for their profession and document how they set the number.
See the IRS guidance on S corporation compensation.
Other effects to consider
- QBI deduction: your W-2 salary doesn’t count as qualified business income, so a higher salary can reduce the 20% QBI deduction.
- Retirement savings: employer contributions to a Solo 401(k) are based on 25% of your W-2 salary, so a low salary limits contributions. See Solo 401(k) vs. SEP IRA.
- Health insurance: premiums for more-than-2% shareholders are handled through payroll (included in W-2 wages) and then generally deductible on your personal return.
- Social Security benefits: paying less into Social Security now can mean lower future benefits.
When an S corp election makes sense
| Probably not yet | Worth evaluating |
|---|---|
| Net profit is under ~$50,000–$60,000 | Net profit is consistently ~$80,000–$100,000+ |
| Income is unpredictable year to year | Income is stable and growing |
| You’re in a state with high S corp costs and modest profit | Savings clearly exceed payroll, accounting and state costs |
| You don’t want to run payroll | You’re comfortable with (or will pay for) payroll and bookkeeping |
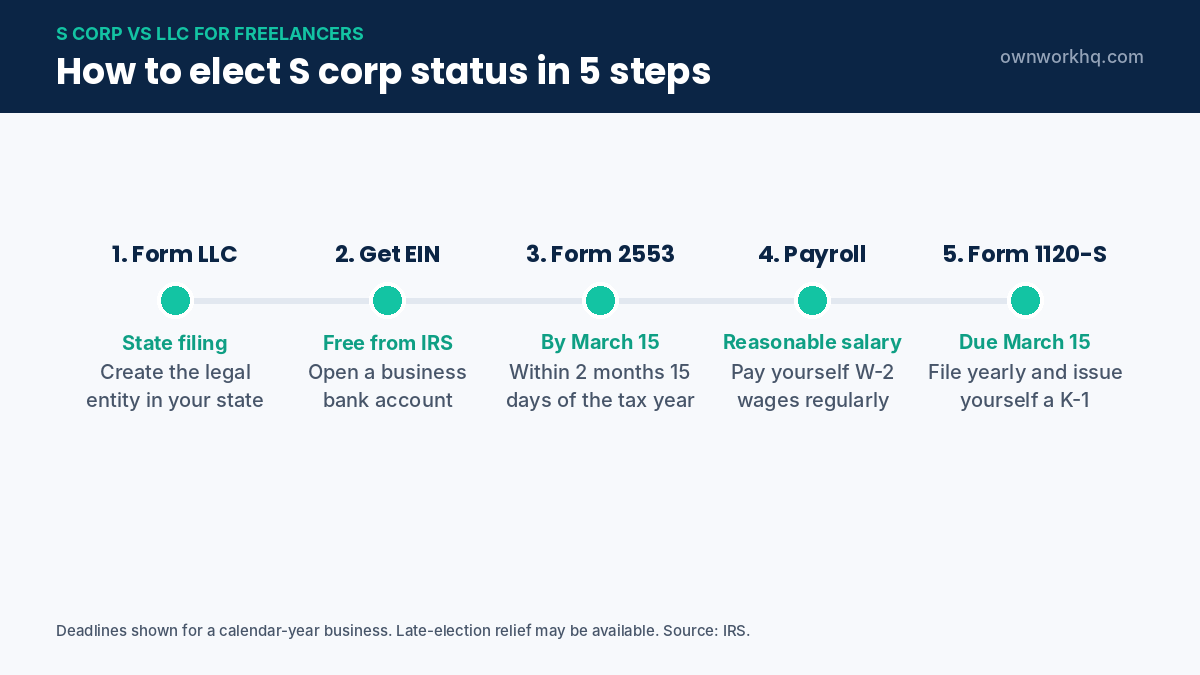
How to elect S corp status
- Form an LLC (or corporation) in your state if you haven’t. See Texas and California guides for examples.
- Get an EIN and open a business bank account. See the best business bank accounts for freelancers.
- File Form 2553 with the IRS, generally no more than 2 months and 15 days after the start of the tax year the election takes effect (late-election relief may be available).
- Set up payroll and pay yourself a reasonable salary on a regular schedule.
- File Form 1120-S each year (due March 15 for calendar-year S corps) and issue yourself a K-1.
- Check state rules, since some states require a separate election or charge additional taxes.
S corp vs LLC for freelancers: the full math (including the QBI catch)
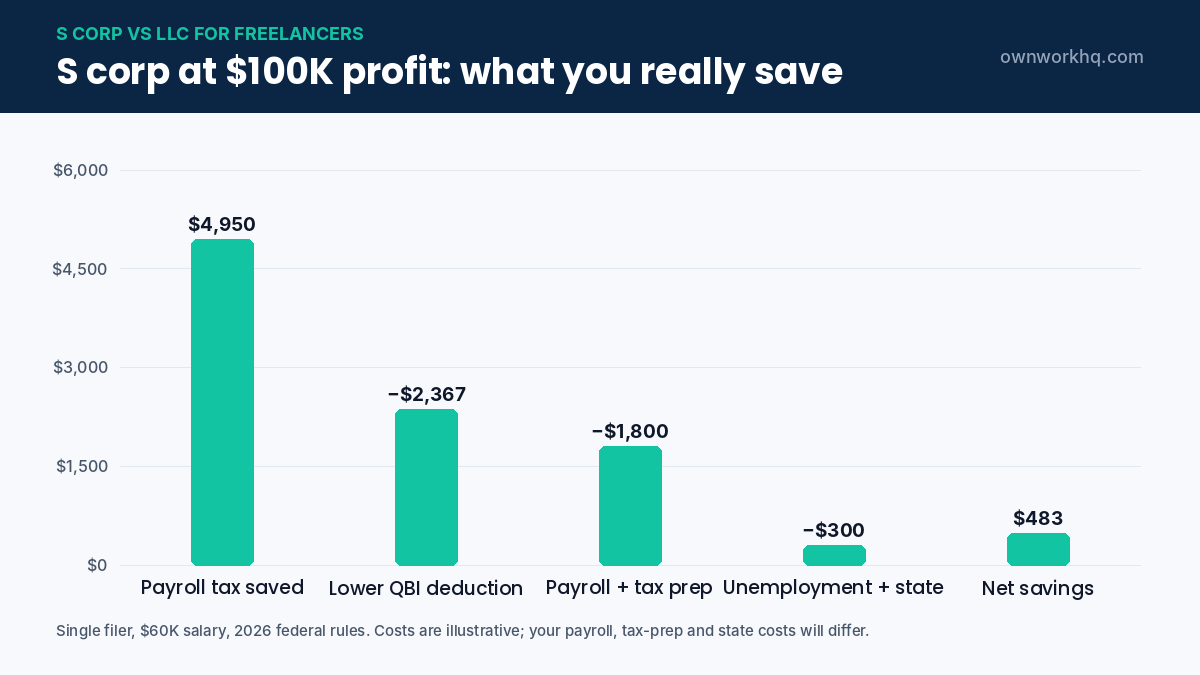
Most S corp comparisons stop at payroll taxes. That overstates the savings, because an S corp also changes your qualified business income (QBI) deduction. Your W-2 salary doesn’t count as QBI, so the 20% deduction shrinks and your income tax goes up. Here’s the full federal picture for a single freelancer in 2026:
| $60K profit ($40K salary) | $100K profit ($60K salary) | $150K profit ($80K salary) | $200K profit ($100K salary) | |
|---|---|---|---|---|
| Total federal tax as default LLC | $12,037 | $22,365 | $37,608 | $53,431 |
| Total federal tax as S corp | $10,366 | $19,782 | $32,439 | $45,765 |
| Payroll tax saved | $2,358 | $4,950 | $8,954 | $12,934 |
| Extra income tax (smaller QBI deduction) | −$687 | −$2,367 | −$3,786 | −$5,269 |
| Savings before running costs | $1,671 | $2,582 | $5,169 | $7,665 |
Our calculation: 2026 brackets, standard deduction, 20% QBI deduction, employer payroll tax deducted by the S corp. Excludes state taxes, unemployment taxes, retirement contributions and health insurance. Salaries are examples, not recommendations.
Now subtract the cost of running an S corp. With roughly $2,100 a year for payroll, tax preparation and other fees, the $100,000 example keeps only about $482. At $150,000 it’s closer to $3,069, and at $200,000 about $5,565. That’s why the S corp vs LLC decision usually tips toward the S corp only at higher, steady profits.
How to set a reasonable salary (with a simple method)
The salary is the lever that decides your S corp savings, and it’s also what the IRS looks at first. There’s no official percentage. Instead, the IRS lists factors such as training and experience, duties and responsibilities, time devoted to the business, what comparable businesses pay for similar services, and the company’s compensation history.
- Find market pay for your role. Look up wages for your occupation and region in the BLS Occupational Employment and Wage Statistics or salary surveys.
- Adjust for your hours. If you work 30 hours a week, scale a full-time salary accordingly.
- Account for non-labor profit. Profit from other people’s work, products or capital supports a lower salary share; profit from your personal services supports a higher one.
- Write it down. Save the data and your reasoning in a one-page memo each year.
- Revisit annually. Raise the salary as your rates and profit rise.
Rules of thumb such as “60/40” are popular online, but they aren’t IRS rules. A salary that’s clearly below market for your work is the most common reason S corp owners get reclassified wages, back taxes and penalties.
Retirement and the S corp vs LLC choice
Your structure also changes how much you can put into a Solo 401(k). As a default LLC, the employer contribution is about 20% of net self-employment earnings. As an S corp, it’s 25% of your W-2 salary only, so a low salary limits what you can save.
| $100K profit | Default LLC | S corp ($60K salary) |
|---|---|---|
| Employee deferral (2026) | $24,500 | $24,500 |
| Employer contribution | About $18,587 | $15,000 (25% × $60,000) |
| Total Solo 401(k) maximum | About $43,087 | $39,500 |
For many freelancers this difference is small, but it matters if maxing out retirement savings is a priority. See Solo 401k vs SEP IRA for the plan details.
S corp election timing: when to make the switch
- Start of the year is cleanest. File Form 2553 by March 15 so the S corp election covers the whole calendar year and you avoid splitting the year between two tax treatments.
- Mid-year elections are possible for a new entity, which can elect within 2 months and 15 days of its start, but they create extra bookkeeping.
- Missed the deadline? The IRS offers late-election relief in many cases if you have reasonable cause (see the Form 2553 instructions).
- Run payroll from the first month. Salary should be paid regularly during the year, not as one lump sum in December.
If your profit is close to the break-even, it’s often smarter to wait one more year and confirm your income is stable before you file for S corp status.
S corp vs LLC: common mistakes freelancers make
- Electing too early. At $40,000–$60,000 of profit, costs often cancel the savings.
- Paying no salary at all. Taking only distributions is the classic red flag.
- Forgetting state costs. Some states charge S corps franchise or entity-level taxes.
- Ignoring the QBI effect. As shown above, it can cut the savings roughly in half.
- Mixing personal and business money. It weakens your liability protection and complicates payroll.
- Not adjusting quarterly estimates. Distributions are still taxable income; plan your quarterly estimated taxes accordingly.
State rules that change the S corp vs LLC math
Federal savings are only part of the story. Your state can add costs or reduce the benefit of an S corp election:
| State example | What changes |
|---|---|
| California | S corps, including LLCs that elect S corp status, pay a 1.5% franchise tax on net income with an $800 minimum. |
| New York City | The city doesn’t recognize the federal S election for its corporate tax, so NYC S corps generally pay city-level corporate tax. |
| Tennessee | LLCs and S corps alike pay franchise and excise taxes, so the comparison is mostly about federal payroll taxes. |
| Texas | No personal income tax. LLCs and S corps both fall under the franchise tax, but most freelancers owe $0 below the no-tax-due threshold. |
Also check state unemployment insurance on your salary and any separate state S election or annual report fees. If you live in a high-cost state, ask a local CPA to rerun the numbers before filing Form 2553.
What an LLC alone does (and does not) do
Many freelancers form an LLC first and only later think about an S corp election. That’s a sensible order, because the two do different jobs:
- Liability protection: an LLC separates business debts and many claims from your personal assets, as long as you keep finances separate. An S corp election doesn’t add to that protection.
- Taxes: a single-member LLC changes nothing on your federal return by default. It’s still Schedule C and self-employment tax.
- Credibility: some larger clients prefer to contract with an entity rather than an individual.
- Costs: state filing and annual fees, which vary widely by state.
In short, the S corp vs LLC question is really two questions: do you need an LLC for protection, and is your profit high enough for S corp taxation to pay off? Answer them separately, and remember that business insurance is still important either way.
Before you elect S corp status, check your current tax bill as a sole proprietor or single-member LLC with our income tax calculator, then compare it with the savings in this guide.
Frequently asked questions
Is an S corp better than an LLC for freelancers?
They aren’t alternatives: an LLC is a legal entity and an S corp is a tax election that an LLC can make. Electing S corp taxation can reduce self-employment tax once your profit is high enough to outweigh the extra costs.
At what income should a freelancer become an S corp?
There’s no single number. Many freelancers start evaluating it when net profit is consistently around $80,000–$100,000 or more. Run the numbers with your state’s costs and a realistic salary, ideally with a CPA.
Can a sole proprietor elect S corp status?
Not directly. You need a legal entity, typically an LLC or corporation, which then files Form 2553 to be taxed as an S corporation.
What happens if my salary is too low?
The IRS can reclassify distributions as wages and assess back payroll taxes, penalties and interest. Document how you determined a reasonable salary.
Can I undo an S corp election?
Yes, you can revoke it, but generally you can’t re-elect for five years without IRS consent. Plan before electing.
Does an S corp lower my income tax?
Not directly. The S corp election mainly reduces Social Security and Medicare taxes. Because your salary doesn’t qualify for the QBI deduction, your income tax can actually go up slightly.
How much does it cost to run an S corp?
Costs vary by state and provider, but freelancers commonly spend several hundred dollars a year on payroll software or services plus more for Form 1120-S preparation, and some states add fees or entity-level taxes. Get quotes before you elect.
Can I switch from an S corp back to an LLC?
Yes. You can revoke the S corp election and return to default LLC taxation, but you generally can’t re-elect S corp status for five years without IRS consent.
Is the S corp vs LLC decision different for married couples?
The tax brackets and QBI limits differ for joint filers, so the break-even point can shift. Run the numbers with your actual filing status and both spouses’ income.
Sources
- IRS: S corporations
- IRS: Form 2553
- IRS: S corporation compensation and medical insurance issues
- California FTB: S corporations
Disclaimer: This article is for informational purposes only and is not tax, legal or financial advice. OwnWork HQ is not a CPA or tax advisor. Tax rules change and depend on your situation, so confirm details with the IRS or a qualified tax professional before you act.
About OwnWork HQ Editorial
We write plain-English guides for US freelancers and check every rate, limit and deadline against IRS and state agency publications. We are not CPAs or financial advisors; for advice on your situation, talk to a qualified professional.