1099 vs W2: What Freelancers Need to Know (Taxes, Benefits & Rates)
In short: 1099 vs W-2 explained for freelancers: how taxes, benefits and control differ, how the IRS classifies workers, and how to compare a 1099 rate with a W-2 salary.

On this page
- 1099 vs W-2: side-by-side comparison
- How the IRS decides: employee or contractor?
- Taxes: what changes when you’re paid on a 1099
- Comparing a 1099 rate to a W-2 salary
- What if you get both a W-2 and 1099s?
- What if you’re misclassified?
- 1099 vs W2 take-home pay: a $75,000 example
- How to convert a W-2 salary into a 1099 rate
- 1099-NEC, 1099-K and 1099-MISC: which forms you might get
- Benefits you give up on a 1099 (and how to replace them)
- Questions to ask before you accept a 1099 role
- Switching from W-2 to 1099: your first-month checklist
- State classification rules: the ABC test
- 1099 vs W2 for side gigs and app-based work
- Frequently asked questions
- Sources
A new client sends you a Form W-9 and says you’ll get a “1099.” A job offer says you’ll be “on W-2.” The difference between 1099 and W-2 isn’t just paperwork: it changes how much tax you pay, who pays for benefits and how much control you have over your work. Here’s what freelancers need to know. This guide breaks down the 1099 vs W2 differences that matter most to freelancers.
Key takeaways
- W-2 = employee. 1099 = independent contractor (freelancer).
- Contractors pay both halves of Social Security and Medicare through self-employment tax, but can deduct half of it and their business expenses.
- For payments made in 2026 and later, clients generally issue Form 1099-NEC only if they pay you $2,000 or more in a year. You owe tax on all income either way.
- Classification depends on behavioral control, financial control and the relationship, per the IRS.
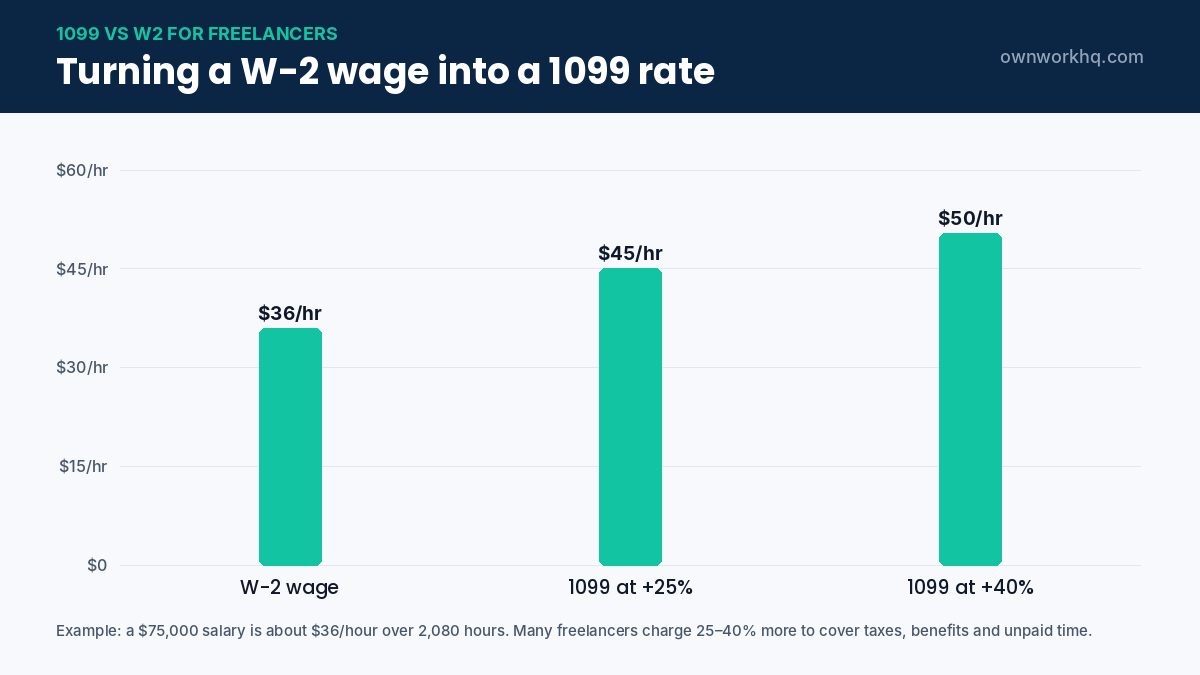
- To compare offers fairly, a 1099 rate usually needs to be 25–40% higher than the equivalent W-2 hourly wage.
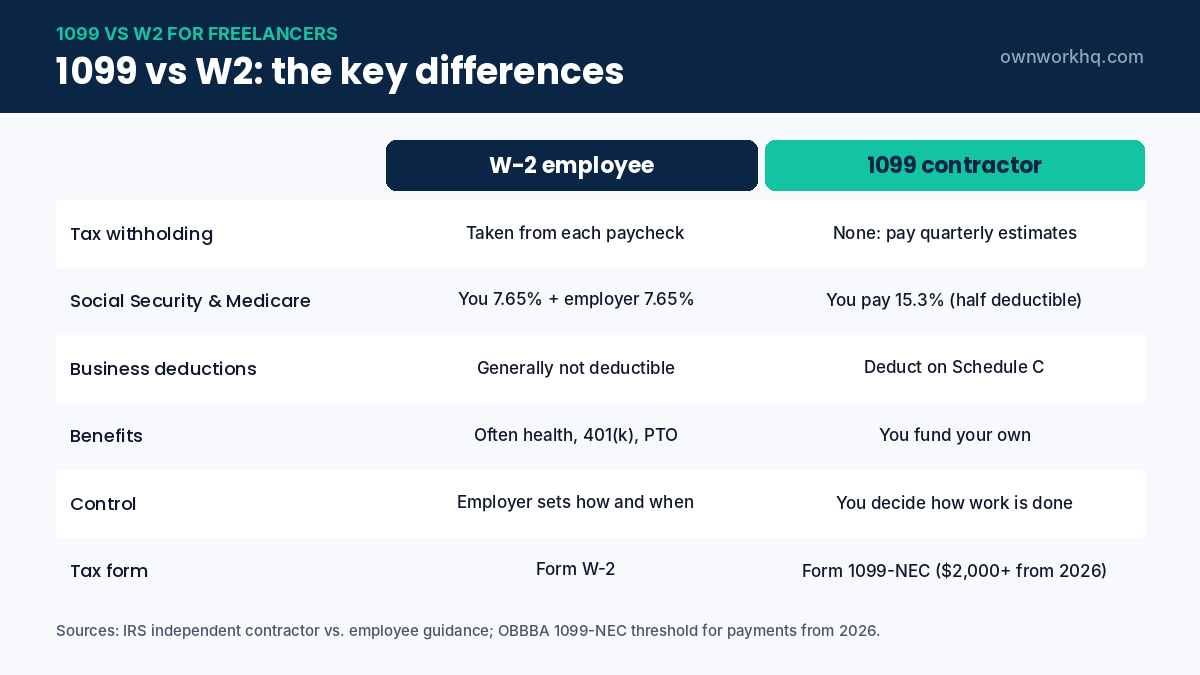
1099 vs W-2: side-by-side comparison
| W-2 employee | 1099 independent contractor | |
|---|---|---|
| Tax form you receive | Form W-2 | Form 1099-NEC (and sometimes 1099-K) |
| Tax withholding | Employer withholds income and payroll taxes | No withholding; you pay estimated taxes quarterly |
| Social Security & Medicare | You pay 7.65%; employer pays 7.65% | You pay 15.3% self-employment tax (half is deductible) |
| Business expense deductions | Generally not deductible for employees | Deductible on Schedule C |
| Benefits | Often health insurance, 401(k) match, paid time off | None from the client; you fund your own |
| Unemployment & workers’ comp | Usually covered | Usually not covered |
| Control over work | Employer controls how, when and where | You control how the work gets done |
| Tools and equipment | Usually provided | You provide your own |
| Number of clients | Usually one employer | Often several clients |
How the IRS decides: employee or contractor?
The IRS looks at the whole relationship, grouped into three categories (see its guide to independent contractor vs. employee):
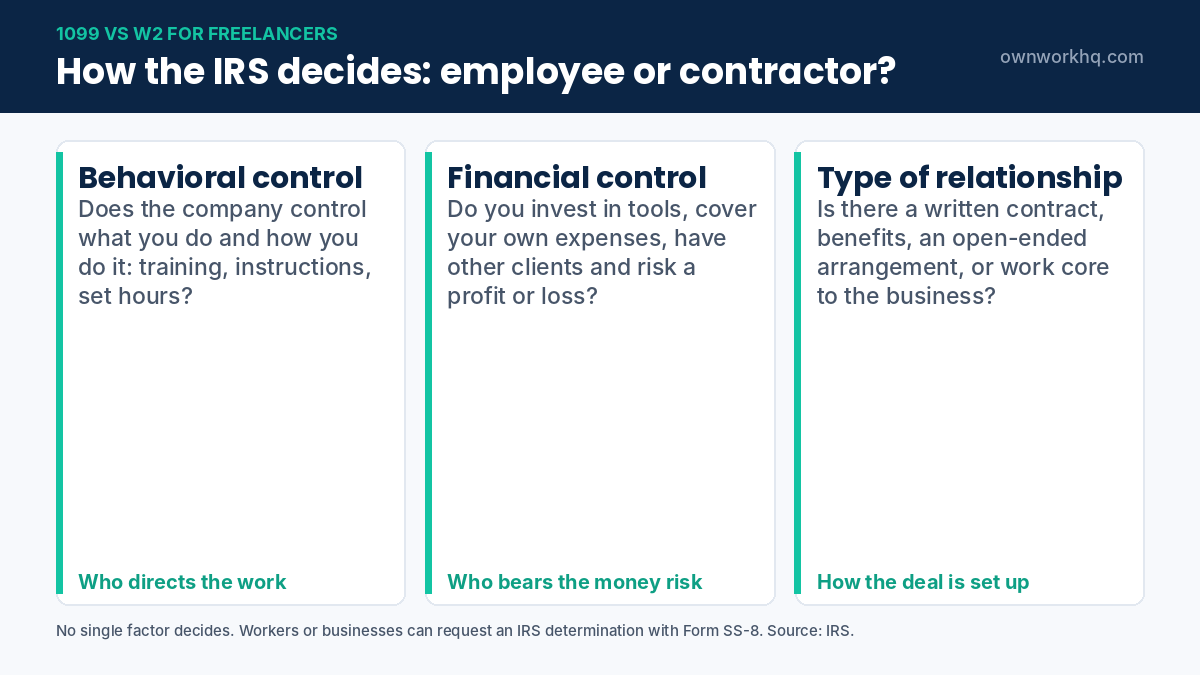
- Behavioral control: does the company control or have the right to control what you do and how you do it (training, instructions, set hours)?
- Financial control: do you have a significant investment, unreimbursed expenses, the ability to make a profit or loss, and other clients? How are you paid?
- Type of relationship: are there written contracts, employee-type benefits, an expectation that the relationship continues indefinitely, and is your work a key part of the company’s regular business?
States can apply stricter tests. California’s “ABC test” is a well-known example. If you’re unsure, the IRS lets workers or businesses request a determination with Form SS-8.
Taxes: what changes when you’re paid on a 1099
Self-employment tax
As a contractor you pay 15.3% on 92.35% of your net earnings: 12.4% for Social Security (up to $184,500 of earnings in 2026) and 2.9% for Medicare. You can deduct half of it when calculating income tax.
Quarterly estimated taxes
Because no one withholds tax, you generally make estimated payments four times a year if you’ll owe $1,000 or more. Our guide to quarterly estimated taxes includes a calculator and the 2027 deadlines.
Deductions
Contractors can deduct ordinary and necessary business expenses: home office, equipment, software, travel, insurance and more. That can substantially reduce taxable income. See examples in tax deductions for freelance writers and tax deductions for photographers.
Comparing a 1099 rate to a W-2 salary
A $50/hour 1099 contract is not the same as a $50/hour W-2 job. As a contractor you cover the employer’s share of payroll taxes, your own benefits, unpaid time off and business costs. A rough way to compare:
| Cost the employer would normally cover | Approximate value |
|---|---|
| Employer’s half of Social Security and Medicare | 7.65% of pay |
| Health insurance | Varies widely; often hundreds of dollars a month |
| Retirement match | Commonly 3–6% of pay |
| Paid holidays, vacation and sick days | Roughly 8–12% of working days |
| Equipment, software, insurance | Your business costs |
Many freelancers aim for a 1099 rate that’s 25–40% higher than the equivalent W-2 hourly wage. For a full method, see our guide to setting freelance rates.
What if you get both a W-2 and 1099s?
Many people have a day job and freelance on the side. You’ll report W-2 wages and 1099 income on the same Form 1040, with your freelance income on Schedule C. You can avoid quarterly payments by increasing withholding at your day job (with a new Form W-4) to cover the tax on your freelance income. Keep in mind the Social Security wage base applies to your combined wages and self-employment earnings.
What if you’re misclassified?
If a company treats you as a contractor but controls your work like an employee, you may be misclassified. You could be missing employer payroll contributions, overtime and benefits. Options include talking to the company, filing Form SS-8 with the IRS for a determination, or using Form 8919 to report uncollected Social Security and Medicare tax on wages. State labor departments can also help.
1099 vs W2 take-home pay: a $75,000 example
What happens if you earn exactly the same amount on a W-2 and on a 1099? Here’s a 2026 federal comparison for a single filer with no other income, using the standard deduction. For the 1099 worker, $75,000 is net profit after business expenses.
| W-2 employee ($75,000 salary) | 1099 contractor ($75,000 profit) | |
|---|---|---|
| Social Security & Medicare | $5,738 (7.65%) | $10,597 (self-employment tax) |
| Deduction for half of SE tax | — | −$5,299 |
| QBI deduction | — | −$10,720 |
| Federal income tax | $7,670 | $4,898 |
| Total federal tax | $13,408 | $15,495 |
| Take-home before benefits | $61,592 | $59,505 |
Our calculation using 2026 IRS brackets and the $16,100 standard deduction. Excludes state tax.
The contractor keeps about $2,087 less, even though the QBI deduction lowers their income tax. And that’s before paying for health insurance, retirement savings and time off, which an employer often covers. This is the core of the 1099 vs W2 trade-off: the same headline number is worth less on a 1099.
How to convert a W-2 salary into a 1099 rate
Use this simple formula to find the 1099 rate that matches a W-2 offer:
1099 hourly rate = (W-2 salary + employer payroll tax + value of benefits + your business costs) ÷ realistic billable hours
- Employer payroll tax: 7.65% of the salary ($5,738 on $75,000).
- Benefits: estimate health insurance, retirement match (often 3–6%) and paid time off.
- Business costs: software, equipment, insurance, accounting.
- Billable hours: 1,000–1,500 a year is common for freelancers, versus 2,080 paid hours for an employee.
Run with real numbers and many freelancers land well above the 25–40% premium rule of thumb, especially if they bill fewer hours. Our guide on how to set freelance rates walks through a complete example.
1099-NEC, 1099-K and 1099-MISC: which forms you might get
| Form | What it reports | Federal threshold |
|---|---|---|
| 1099-NEC | Payments for your services from a business client | $2,000 or more for payments made from 2026 (was $600) |
| 1099-K | Payments through card processors and payment apps | Over $20,000 and more than 200 transactions |
| 1099-MISC | Other payments such as rents, prizes and royalties | $2,000 or more for most payments from 2026 |
| W-2 | Wages from an employer, with taxes withheld | Any wages paid to an employee |
Thresholds only decide when a payer must send a form. In the 1099 vs W2 question, the rule for you is simple: all income is taxable, with or without a form. Learn more in what is a 1099-NEC form.
Benefits you give up on a 1099 (and how to replace them)
| Benefit | W-2 employee | How a 1099 contractor replaces it |
|---|---|---|
| Health insurance | Employer usually pays a large share | Marketplace plan, deductible premiums: see health insurance for self-employed freelancers |
| Retirement match | Often 3–6% of pay | Solo 401(k) or SEP IRA: see Solo 401k vs SEP IRA |
| Paid time off | Vacation, holidays, sick days | Build unpaid weeks into your rate |
| Unemployment insurance | Usually covered | Emergency fund of 3–6 months of expenses |
| Workers’ compensation | Usually covered | Disability insurance and, if needed, business insurance |
Questions to ask before you accept a 1099 role
- Will I set my own hours and decide how the work gets done?
- Can I work for other clients at the same time?
- Who provides the equipment and software?
- Is the rate high enough to cover self-employment tax, benefits and unpaid time?
- How and when will I be paid, and what are the late-payment terms in the contract?
- Is the role open-ended and central to the company’s business? If so, ask why it isn’t a W-2 position.
If most answers point to the company controlling your work, the role may really be employment. Weighing 1099 vs W2 offers with these questions protects your income and helps you spot misclassification early. A clear freelance contract also helps.
Switching from W-2 to 1099: your first-month checklist
- Give clients a Form W-9 with your Social Security number or, better, an EIN. See how to get an EIN.
- Open a separate business bank account so client payments never mix with personal spending.
- Start a tax savings account and set aside 25–30% of every payment.
- Calendar your quarterly estimated tax dates. The next one is probably closer than you think.
- Arrange health insurance before your employer coverage ends.
- Use a written contract for every client, with scope, payment terms and late fees.
- Set up invoicing and bookkeeping from day one. A simple freelance invoice template is enough to start.
Doing these seven things in your first month avoids the most common surprises of the 1099 vs W2 transition: an unexpected tax bill, a gap in coverage and messy records at tax time.
State classification rules: the ABC test
The IRS test isn’t the only one that matters. Several states use a stricter ABC test for some purposes, such as unemployment insurance or wage laws. Under it, you’re presumed to be an employee unless all three conditions are met:
- A: you’re free from the company’s control and direction in performing the work.
- B: the work is outside the usual course of the company’s business.
- C: you’re customarily engaged in an independently established trade or business of the same kind.
California is the best-known example, with exemptions for many professional services. Massachusetts and New Jersey also apply versions of the ABC test. If you work for clients in these states, read your contract carefully and keep evidence of your independent business, such as other clients, your own website and your own tools.
1099 vs W2 for side gigs and app-based work
Driving, delivery and marketplace apps almost always treat you as an independent contractor. Payments may arrive on a 1099-NEC from the company or a 1099-K from the payment processor, and some months you may get no form at all. The rules are the same as for any freelancer: report all of it on Schedule C, deduct your real business costs and pay self-employment tax on the profit.
If you also have a W-2 job, the simplest approach is often to raise your withholding with a new Form W-4 instead of making separate estimated payments. Keep a mileage log and receipts from the start, because vehicle costs are usually the largest deduction for app-based work.
To compare your own numbers, enter your salary or 1099 profit in our free income tax calculator. It shows FICA or self-employment tax, federal and state income tax side by side.
Frequently asked questions
Is it better to be paid on a 1099 or a W-2?
It depends. W-2 employment offers withholding, the employer’s share of payroll taxes and often benefits. 1099 work offers flexibility, multiple clients and business deductions, but you need to charge enough to cover taxes and benefits yourself.
Do I have to pay taxes if I don’t receive a 1099?
Yes. All self-employment income is taxable whether or not you receive a Form 1099. For payments in 2026 and later, clients only have to issue a 1099-NEC if they pay you $2,000 or more, so keep your own records.
How much should I set aside from 1099 income?
Many freelancers set aside 25–30% of net profit for federal taxes, plus state income tax if applicable. Use a calculator to fine-tune the percentage.
Can I be both a W-2 employee and a 1099 contractor for the same company?
It’s possible in limited cases where the contract work is genuinely separate from your job duties, but it raises classification questions. Check with a tax professional.
What’s the difference between Form 1099-NEC and 1099-K?
Form 1099-NEC reports nonemployee compensation paid directly by clients. Form 1099-K reports payments received through payment apps and card processors when they exceed federal reporting thresholds.
Is 1099 or W2 better for taxes?
Neither is automatically better. W-2 employees pay only half of Social Security and Medicare; 1099 contractors pay the full 15.3% but can deduct business expenses and may claim the QBI deduction. At the same pay, a W-2 job usually leaves you with more after tax and benefits.
Can W-2 employees deduct work expenses?
Generally no. Unreimbursed employee expenses aren’t deductible on federal returns, and the 2025 federal tax law made that rule permanent. Contractors, by contrast, deduct ordinary and necessary business expenses on Schedule C.
How do I know if I should be a W-2 employee instead of a 1099 contractor?
Look at control: if the company sets your hours, methods and tools and the work is ongoing and central to its business, you may be an employee. You can ask the IRS for a determination with Form SS-8.
Do 1099 contractors get unemployment benefits?
Usually not, because clients don’t pay unemployment taxes on contractor payments. Some states have special programs, so check your state labor department.
Does a 1099 contractor need an EIN?
Not legally in most cases, because you can use your Social Security number on Form W-9. Many freelancers still get a free EIN from the IRS so they don’t have to share their SSN with every client, and some banks require one for a business account.
Can I deduct health insurance as a 1099 contractor?
Usually yes. If you have a net profit and weren’t eligible for an employer-subsidized plan, you can deduct premiums for yourself, your spouse and dependents as an adjustment to income using Form 7206.
How long should I keep records of 1099 income?
Keep invoices, bank statements, receipts and copies of any 1099 forms for at least three years after you file, which is the general IRS period for audits. Keep records longer if you underreported income or claimed bad debts.
Sources
- IRS: Independent contractor (self-employed) or employee?
- IRS: Self-employment tax
- IRS: Form SS-8
- Paylocity: 1099 reporting threshold increased to $2,000
Disclaimer: This article is for informational purposes only and is not tax, legal or financial advice. OwnWork HQ is not a CPA or tax advisor. Tax rules change and depend on your situation, so confirm details with the IRS or a qualified tax professional before you act.
About OwnWork HQ Editorial
We write plain-English guides for US freelancers and check every rate, limit and deadline against IRS and state agency publications. We are not CPAs or financial advisors; for advice on your situation, talk to a qualified professional.