Health Insurance for Self-Employed Freelancers (2027 Guide): Options, Subsidies & Deductions
In short: How self-employed freelancers can get health insurance for 2027: Marketplace plans after the enhanced subsidies expired, open enrollment dates, the self-employed health insurance deduction and HSAs.

On this page
- Health insurance for self-employed freelancers: your options
- How ACA Marketplace subsidies work in 2027
- Estimating income as a freelancer (without getting burned)
- The self-employed health insurance deduction
- Health Savings Accounts (HSAs) for freelancers
- How to choose a plan as a freelancer
- Budgeting for health insurance
- How much does health insurance for self-employed freelancers cost?
- Marketplace metal levels: which tier fits a freelancer?
- How to lower the cost of self-employed health insurance
- Special enrollment: getting covered outside open enrollment
- Health insurance if you have an LLC or S corp
- Step-by-step: how to enroll in a Marketplace plan
- COBRA vs a Marketplace plan when you start freelancing
- Frequently asked questions
- Sources
Health insurance is the benefit freelancers miss most after leaving a job, and in 2027 it’s more expensive for many people. The enhanced ACA premium tax credits expired at the end of 2025, which means higher premiums for many self-employed people with moderate or higher incomes. The good news: you still have solid options, and the premiums can be tax deductible. Here’s how health insurance for self-employed freelancers works for 2027 coverage.
Key takeaways
- Marketplace plans are the main option. Premium tax credits are based on your estimated income.
- The enhanced subsidies expired after 2025, so the “cliff” at 400% of the federal poverty level is back for 2027.
- Starting with tax year 2026, you must repay any excess advance credits in full if your income ends up higher than estimated.
- Self-employed people can usually deduct health insurance premiums above the line (Form 7206).
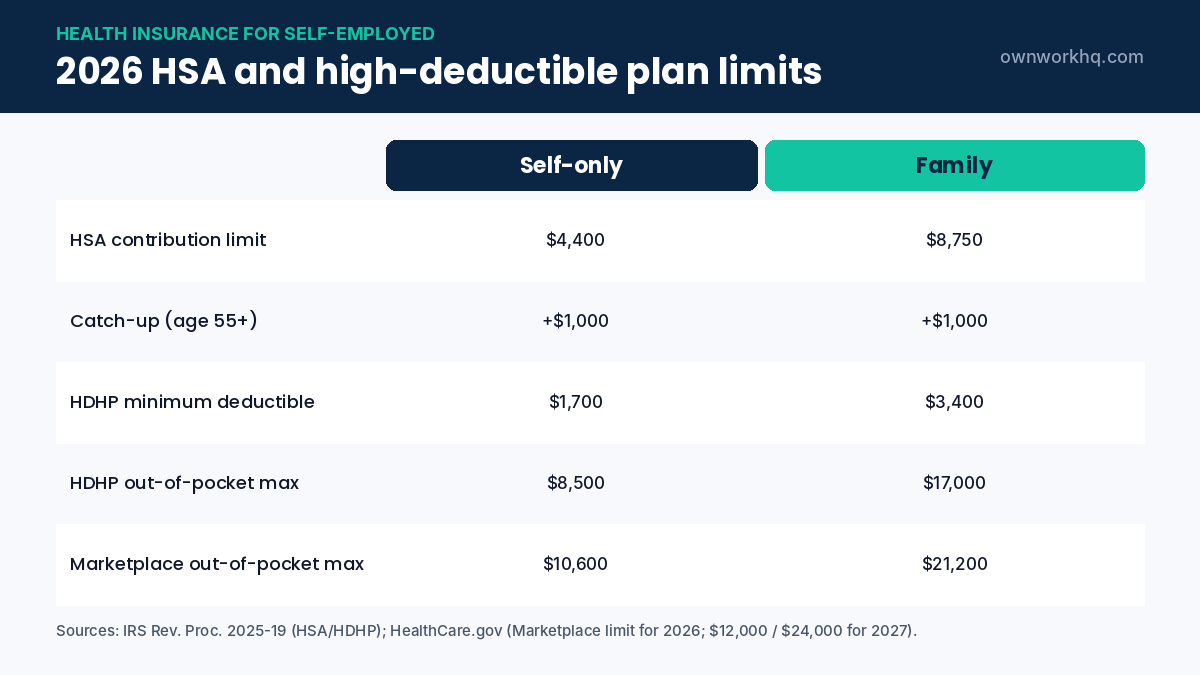
- Pairing an HSA-eligible plan with a Health Savings Account adds another tax break ($4,400 self-only / $8,750 family in 2026).
Health insurance for self-employed freelancers: your options
| Option | Best for | Pros | Cons |
|---|---|---|---|
| ACA Marketplace plan | Most freelancers | Can’t be denied for pre-existing conditions; premium tax credits based on income | Premiums are high above the subsidy limit; networks vary |
| Spouse’s or partner’s employer plan | Freelancers with an employed spouse | Employer pays part of the premium; often broader networks | Depends on the spouse’s employer; blocks the self-employed deduction |
| COBRA | Recently left a job | Keep the same plan and doctors for up to 18 months | Usually expensive: you pay the full premium plus a fee |
| State-specific programs / Medicaid | Low or uneven income | Low or no cost if eligible | Income limits; coverage varies by state |
| Short-term health plans | Brief gaps between coverage | Cheaper premiums | Not ACA-compliant; can exclude pre-existing conditions |
| Health care sharing ministries | Some faith-based freelancers | Lower monthly cost | Not insurance; no guarantee of payment |

How ACA Marketplace subsidies work in 2027
Premium tax credits lower your monthly premium based on your estimated household income and family size. For 2027, according to BenefitChamps, the original ACA rules apply again:
- Credits are generally available for household income between 100% and 400% of the federal poverty level. Above 400%, there’s no premium tax credit (the “subsidy cliff”).
- The percentage of income you’re expected to pay for the benchmark plan is higher than under the 2021–2025 enhanced rules.
- Starting with tax year 2026, the caps on repaying excess advance credits are eliminated. If your income ends up higher than estimated, you repay the full difference when you file.
Status check: as of September 2026, a three-year extension of the enhanced credits had passed the House but not the Senate. Check HealthCare.gov for the latest rules before you enroll.
Estimating income as a freelancer (without getting burned)
Because subsidies depend on income you haven’t earned yet, freelancers need to estimate carefully:
- Use net self-employment income (after business expenses) as the starting point for your household’s modified adjusted gross income.
- Be realistic, not optimistic or pessimistic. Underestimating can mean a big repayment now that the caps are gone.
- Report income changes on HealthCare.gov during the year so your advance credit adjusts.
- Remember that deductions lower MAGI. Contributions to a pre-tax Solo 401(k) or SEP IRA can reduce your MAGI and may increase your subsidy.
The self-employed health insurance deduction
If you’re self-employed with a net profit, you can generally deduct premiums for medical, dental and qualifying long-term care insurance for yourself, your spouse and your dependents as an adjustment to income, using Form 7206. Key rules from the IRS:
- The deduction can’t exceed your net self-employment profit from the business under which the plan is established.
- You can’t take it for any month you were eligible for an employer-subsidized plan, including through a spouse’s employer.
- Premiums paid with premium tax credits aren’t deductible. Only the part you actually paid counts.
- It reduces income tax but not self-employment tax.
See the IRS page for Form 7206 for the full rules.
Health Savings Accounts (HSAs) for freelancers
An HSA lets you contribute pre-tax money for medical expenses if you have an HSA-eligible health plan. For 2026, the limits are $4,400 for self-only coverage and $8,750 for family coverage, plus a $1,000 catch-up at age 55+. Contributions are deductible, growth is tax-free and withdrawals for qualified medical expenses are tax-free.
Under the 2025 federal tax law, bronze and catastrophic Marketplace plans are treated as HSA-compatible starting in 2026, which gives more freelancers access to an HSA. Confirm eligibility with your plan before contributing.
How to choose a plan as a freelancer
- Check your doctors and prescriptions in the plan’s network and formulary.
- Compare total cost, not just the premium: add the deductible and expected copays.
- Consider an HSA-eligible plan if you’re generally healthy and want the extra tax break.
- Look at out-of-pocket maximums, which cap your worst-case year.
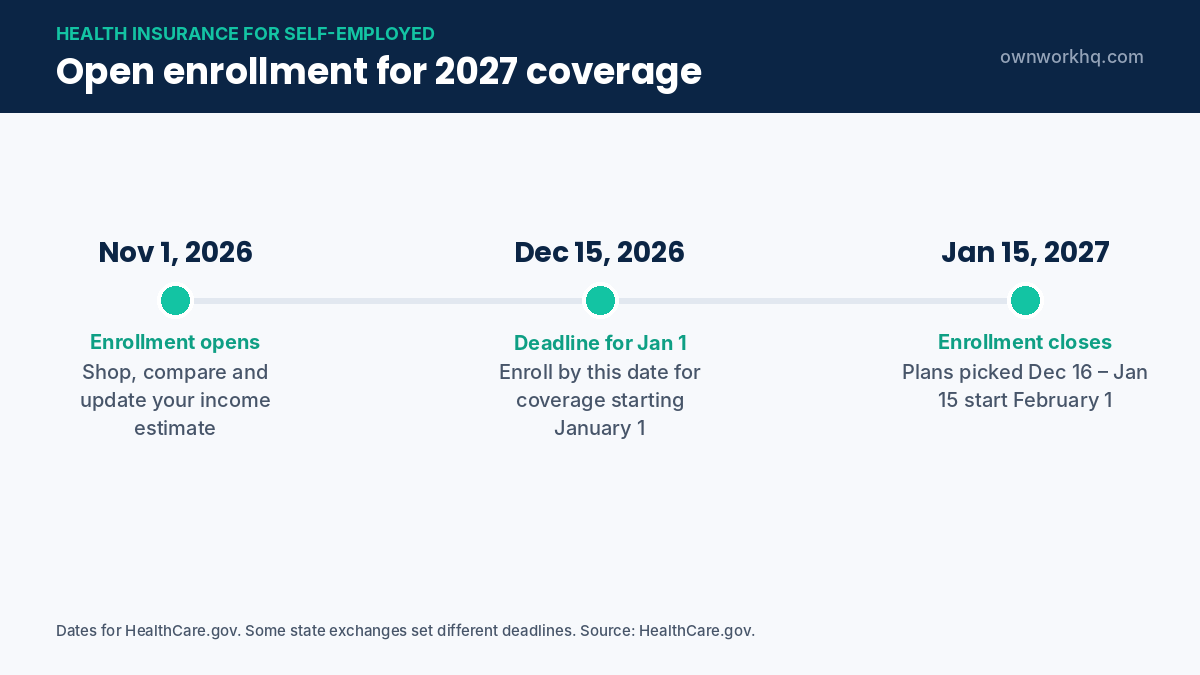
- Enroll by December 15 for January 1 coverage, or within 60 days of a qualifying life event, such as losing job-based coverage.
Budgeting for health insurance
Health insurance is often a freelancer’s second-largest fixed cost after rent. Build it into your rates. Our guide to quarterly estimated taxes explains how to set money aside, and the same “separate account” approach works well for premiums and HSA contributions.
How much does health insurance for self-employed freelancers cost?
Prices depend on your age, ZIP code, household size, tobacco use and the plan level you pick. As a reference point, the national average benchmark premium (the second-lowest-cost silver plan) for a 40-year-old was about $625 a month in 2026, according to KFF data reported by Becker’s. What you actually pay is that price minus any premium tax credit.
Because the enhanced subsidies ended, the income you report now matters even more. For 2027 coverage, Marketplace eligibility uses the 2026 federal poverty guidelines, so the 400% “cliff” sits at about $63,840 for a single person and $132,000 for a family of four, per HealthInsurance.org.
| Household | 100% of poverty level | 400% of poverty level (subsidy cliff) |
|---|---|---|
| 1 person | $15,960 | $63,840 |
| 2 people | $21,640 | $86,560 |
| 4 people | $33,000 | $132,000 |
2026 HHS poverty guidelines for the 48 contiguous states, used for 2027 Marketplace coverage. Alaska and Hawaii have higher figures. If your projected income lands just above a cliff, a pre-tax retirement contribution can bring it back below (see the strategies further down).
Marketplace metal levels: which tier fits a freelancer?
Every Marketplace plan covers the same essential health benefits. The metal level only changes how you and the insurer split costs.
| Tier | Insurer pays on average | Premium | Good fit if you… |
|---|---|---|---|
| Bronze | About 60% | Lowest | Rarely see a doctor and want protection against big bills; many are HSA-eligible from 2026 |
| Silver | About 70% | Medium | Qualify for cost-sharing reductions (income up to 250% of the poverty level), which lower deductibles |
| Gold | About 80% | Higher | Expect regular care or prescriptions and prefer predictable costs |
| Platinum | About 90% | Highest | Have high, ongoing medical costs (not offered in every state) |
| Catastrophic | Very high deductible | Low | Are under 30 or qualify for a hardship exemption |
For many healthy freelancers, a bronze plan paired with an HSA is the lowest-cost way to stay covered. If your income is modest, check silver first: cost-sharing reductions only apply to silver plans and can make them better value than bronze.
How to lower the cost of self-employed health insurance
- Lower your MAGI with retirement savings. Pre-tax contributions to a Solo 401(k) or SEP IRA reduce the income used for subsidies. Compare the two in our Solo 401k vs SEP IRA guide.
- Fund an HSA. HSA contributions are also deductible and further reduce MAGI.
- Deduct your premiums. The self-employed health insurance deduction lowers income tax on the part of the premium you pay.
- Update your income estimate. Report changes on HealthCare.gov during the year to avoid a large repayment.
- Check state help. Some state exchanges add their own subsidies on top of federal credits.
- Shop every year. Prices and networks change each fall; auto-renewing can cost you hundreds of dollars.
- Use preventive care. ACA plans cover recommended preventive services at no cost in network.
Special enrollment: getting covered outside open enrollment
Missed open enrollment? You can still buy a Marketplace plan if you have a qualifying life event. You usually have 60 days from the event to enroll. Events that often apply to freelancers:
- Losing job-based coverage, for example when you quit to freelance full time. Voluntarily dropping COBRA outside open enrollment does not count.
- Moving to a new ZIP code or county with different plans.
- Marriage, birth or adoption.
- Losing Medicaid or CHIP eligibility.
Tip: if you’re planning to leave a job, line up your Marketplace application before your last day so there’s no gap in coverage. Your options for health insurance for self-employed workers are widest right after you lose employer coverage.
Health insurance if you have an LLC or S corp
- Single-member LLC (default tax treatment): nothing changes. You buy coverage as an individual and take the self-employed health insurance deduction.
- S corporation owner (more than 2%): the company pays or reimburses premiums and includes them in your W-2 wages. You then generally deduct them on your personal return.
- HRAs such as QSEHRA or ICHRA: designed for employees. Sole proprietors and more-than-2% S corp shareholders generally can’t use them for their own coverage.
If you’re weighing an S corp election, factor health insurance into the math in our guide to S corp vs LLC for freelancers.
Step-by-step: how to enroll in a Marketplace plan
- Gather your Social Security number, last tax return and a realistic net-profit estimate for next year.
- Go to HealthCare.gov or your state’s exchange and create an account.
- Enter household and income details. Use your expected net self-employment income, not gross revenue.
- Compare plans by total yearly cost: premium × 12 + deductible + expected copays.
- Check that your doctors, hospitals and prescriptions are in network.
- Choose how much of the premium tax credit to take in advance. Taking less upfront lowers the risk of a repayment.
- Enroll by December 15, 2026 for January 1 coverage, then pay your first premium on time.
COBRA vs a Marketplace plan when you start freelancing
If you’re leaving a job to freelance, you’ll usually be offered COBRA. It lets you keep exactly the same plan, but you pay the full premium plus up to a 2% administrative fee, with no employer contribution. That’s often several times what you paid as an employee.
| COBRA | Marketplace plan | |
|---|---|---|
| Plan and doctors | Same plan, same network | New plan; check the network |
| Cost | Full premium + up to 2% | Premium minus any tax credit |
| Subsidies | None | Premium tax credits if eligible |
| Deductible progress | Keeps what you already paid this year | Starts from zero |
| How long | Usually up to 18 months | As long as you stay eligible |
COBRA can make sense if you’ve already met most of this year’s deductible, you’re in the middle of treatment, or your income is too high for tax credits and the Marketplace price is similar. Otherwise, a Marketplace plan is usually cheaper. Losing job-based coverage qualifies you for a special enrollment period, so compare both within 60 days. Don’t wait: once you choose COBRA and then drop it outside open enrollment, you generally can’t switch to a Marketplace plan until the next open enrollment.
Whichever route you choose, budget for the premium every month and treat it like rent: health insurance for self-employed workers is a fixed cost of doing business, and your rates should cover it.
Self-employed health insurance premiums reduce your income tax. Enter them in our income tax calculator to see the effect on your federal and state tax.
Frequently asked questions
When is open enrollment for 2027 health insurance?
On HealthCare.gov, open enrollment for 2027 coverage runs from November 1, 2026 to January 15, 2027. Enroll by December 15 for coverage starting January 1. Some state exchanges have different dates.
Can self-employed people deduct health insurance premiums?
Generally yes. If you have a net profit and aren’t eligible for an employer-subsidized plan, you can deduct premiums for yourself, your spouse and dependents as an adjustment to income using Form 7206.
Did the enhanced ACA subsidies expire?
Yes. The enhanced premium tax credits expired at the end of 2025. As of September 2026, an extension had passed the House but not the Senate. Check HealthCare.gov for current rules.
What happens if my freelance income is higher than I estimated?
You’ll reconcile your advance premium tax credit on your tax return using Form 8962. Starting with tax year 2026, you must repay the full excess, so update your income estimate during the year if it changes.
Are short-term health plans a good idea for freelancers?
They can bridge short gaps, but they aren’t ACA-compliant and may exclude pre-existing conditions or cap benefits. Most freelancers are better protected with a Marketplace plan.
What is the cheapest health insurance for self-employed people?
For many people it’s a Marketplace bronze plan after premium tax credits, or a silver plan if you qualify for cost-sharing reductions. If your income is low enough, Medicaid may cost little or nothing. Short-term plans look cheap but aren’t ACA-compliant.
Can I get health insurance through my LLC?
A single-member LLC doesn’t change your options: you still buy individual coverage and deduct the premiums. Group plans generally require at least one employee other than the owner and spouse.
Is health insurance for self-employed people tax deductible?
Usually yes. If you have a net profit and weren’t eligible for an employer-subsidized plan, you can deduct premiums for yourself, your spouse and dependents as an adjustment to income on Form 7206.
How do I estimate income for a Marketplace plan as a freelancer?
Start with last year’s net profit from Schedule C, adjust for known changes, subtract expected deductions such as half of self-employment tax and pre-tax retirement contributions, and update the estimate during the year if your income changes.
Can I use an HSA with a Marketplace bronze plan?
Starting in 2026, federal law treats bronze and catastrophic Marketplace plans as HSA-compatible. Check with the insurer that your specific plan qualifies before you contribute.
Sources
- HealthCare.gov
- BenefitChamps: What changed for 2027 open enrollment (September 2026)
- Health Affairs: Extending enhanced premium tax credits
- IRS: Form 7206, Self-employed health insurance deduction
- 2026 HSA limits
- RSM: IRS notice on expanded HSA eligibility under OBBBA
Disclaimer: This article is for informational purposes only and is not insurance, legal or financial advice. OwnWork HQ is not a licensed insurance agent. Coverage, prices and eligibility vary by insurer and state and can change at any time, so always confirm details with the insurer or a licensed broker before you buy.
About OwnWork HQ Editorial
We write plain-English guides for US freelancers and check every rate, limit and deadline against IRS and state agency publications. We are not CPAs or financial advisors; for advice on your situation, talk to a qualified professional.